

Connectivity
Vodacom targets mobile money gap in SA
Changes to banking regulations could allow Vodacom to bring more of its African financial services innovations to South Africa, writes ARTHUR GOLDSTUCK.

South Africa could be poised for a major expansion of mobile financial services, with Vodacom eyeing new licensing arrangements that would allow it to introduce products already operating successfully elsewhere in Africa.
Vodacom Group CEO Shameel Joosub said on Tuesday that proposed mobile money licences would be attractive to the company, allowing it to develop financial products independently of traditional banking partners.
The opportunity comes as Vodacom’s financial services business across Africa reaches 108-million customers, processing more than US$575-billion in transactions annually.
Speaking during Vodacom’s interim results presentation, Joosub told Gadget that the company had developed a different financial services model for South Africa, reflecting the country’s extensive banking infrastructure.
“We’ll do almost R4-billion this year in financial services in South Africa, and with a very good margin,” said Joosub. “What we’ve done is carved out a different place. One of the reasons that M-Pesa grew was the lack of banking infrastructure, which we don’t suffer from in South Africa.”
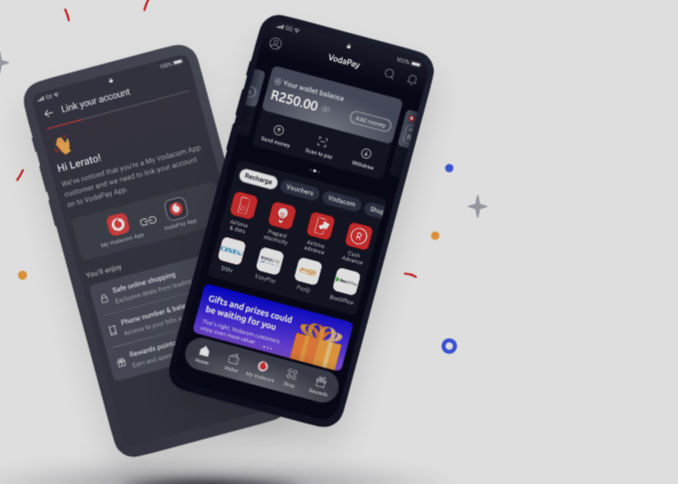
Instead, Vodacom has developed financial products that complement the established banking system, including insurance, credit and merchant payment services.
“We do airtime lending, we do insurance, we do funeral cover, we do merchant acquiring, we do lending. It’s a different play for us.”
The company has already built a substantial customer base for these services, with 15-million South Africans using at least one of its financial products. Joosub said the model was also contributing to financial inclusion by expanding access to financial services for small businesses.
“We’re empowering those merchants, giving them access to lending, and then of course the same with our insurance products.”
A new licensing opportunity
The next opportunity could come from changes to the regulatory environment.
The South African Reserve Bank has been examining ways to expand access to the national payments system and enable non-bank financial services providers to play a greater role in digital payments.
During the results briefing, Joosub told the media: “The mobile money licences will definitely be attractive for us, because one of the things that we have in the other countries, which we don’t have in South Africa, is that in South Africa we have to work through other banks.”
At present, Vodacom relies on banking partners to support the development and operation of financial products. This can slow the introduction of services that the company already offers in other African markets.
“Today, every product that we create, we’ve got to go to the bank. Then we’ve got to wait for the development of the bank. They’re going to develop the product for us, and so on. If the bank is slow, as an example, then you wait in the queue.
“If you can create your own product, some of the products that we do in our international markets we’ll be able to adapt faster into the South African context.”
Vodacom clarified that a central issue was the ability to hold customers’ electronic wallet funds independently of banking intermediaries, subject to the appropriate regulatory safeguards.
“The main thing is the e-wallet money, because of the sensitivity around deposit-taking. That will allow us to obviously not have to have an intermediary going forward.”
From mobile money to mobile finance
Vodacom’s financial services operations across Africa provide an indication of the potential range of products.
The Group’s expanded involvement in Safaricom, the Kenyan telecommunications company behind M-Pesa, dramatically increased the contribution of financial services to its business.
According to Vodacom’s interim results for the six months ended 30 September 2026, the combined financial services operations generated R43.1-billion in pro-forma revenue over the previous 12 months. Financial services revenue grew 19.2% on a comparable pro-forma basis during the six-month reporting period, reflecting growth across the enlarged business. The 108-million financial services customers represent an increase of 15% year on year.
Vodacom’s financial services offering has also expanded beyond person-to-person money transfers, with products designed to support merchants and small businesses. In several African markets, M-Pesa allows individuals to operate separate personal and merchant profiles, enabling small traders to receive payments and conduct business transactions through their phones. The company has been adding services that extend these relationships into business finance.
In Kenya, the company has introduced measures that include free transactions below certain thresholds, aimed at making mobile payments more accessible to smaller merchants. These developments point to a broader opportunity for South Africa, where access to bank accounts is relatively widespread but affordable credit and financial services remain difficult to obtain for many smaller businesses.
A mobile financial services ecosystem built around merchant payments and access to working capital could help address that gap, particularly if providers gain greater freedom to develop products independently.
A different route to financial inclusion
South Africa’s banking infrastructure has produced a different market from those in which M-Pesa originally flourished.
“We didn’t see the opportunity with M-Pesa. In fact, we shut it down probably twice, to be frank,” said Joosub.
He made it clear that the South African opportunity was substantial, even if it followed a different model from M-Pesa.
“We think we’ve been very successful, but it’s not going to be M-Pesa.”
* Arthur Goldstuck is CEO of World Wide Worx, editor-in-chief of Gadget.co.za, and author of “The Hitchhiker’s Guide to AI – The African Edge”.