


Hardware
Global smartphone market shrinks
Rising memory and storage costs have reshaped the competitive landscape, resulting in a 20% plunge in shipments, writes GUIDO RUSSO.

Global smartphone shipments fell 20% year on year in the third quarter of 2026, revealing a sharp downward acceleration from the 6% decline recorded in the previous quarter.
According to preliminary estimates from technology research and advisory group Omdia, shipments continued to decline despite new flagship launches and channel preparations for the year-end festive season.
The reason? Persistent memory and storage cost pressures, which have constrained pricing flexibility and prompted vendors to scale back shipments of low-margin devices.
The downturn has further polarised the competitive landscape. Samsung and Apple together accounted for 45% of global shipments, up approximately 8% from a year earlier. Their relative resilience compared with sharper declines among mass-market-focused competitors indicate that the current downturn is reshaping competitive positions.

Samsung retained the top position with a 23% market share, gaining share despite a year-on-year decline in shipments. Its broad product portfolio and established global channel presence helped cushion the impact of the market downturn, while the August launch of the Galaxy Z Fold8 and Flip8 series supported its premium positioning.
Looking ahead, balancing shipment scale with portfolio profitability and “premiumisation” will be increasingly important to sustaining Samsung’s competitive position.
Apple ranked second with a 22% market share, showing strong resilience despite the wider market downturn. Continued demand for the iPhone 17 family, alongside the September introduction of the iPhone 18 Pro and Pro Max, helped maintain its momentum.
The iPhone Duo marks Apple’s entry into the foldable smartphone category, expanding its portfolio beyond traditional form factors and creating new opportunities to address evolving consumer needs and capture incremental demand. While AI is not yet a major purchase driver for consumers, Apple Intelligence could play an increasingly important role in differentiating Apple’s user experience and sustaining its long-term ecosystem advantage.
Xiaomi maintained third position with 12% market share, followed by Oppo, including realme and OnePlus, at 9%. vivo completed the top five with an 8% share. Rising memory costs are putting pressure on profitability across price segments, with the impact particularly pronounced in more price-sensitive categories.
These pressures are forcing vendors to reassess the profitability of their entry-level portfolios and make more selective decisions about product positioning, pricing and market coverage. Vendors are prioritising average selling price (ASP) growth and portfolio optimisation to sustain shipment value and protect profitability.

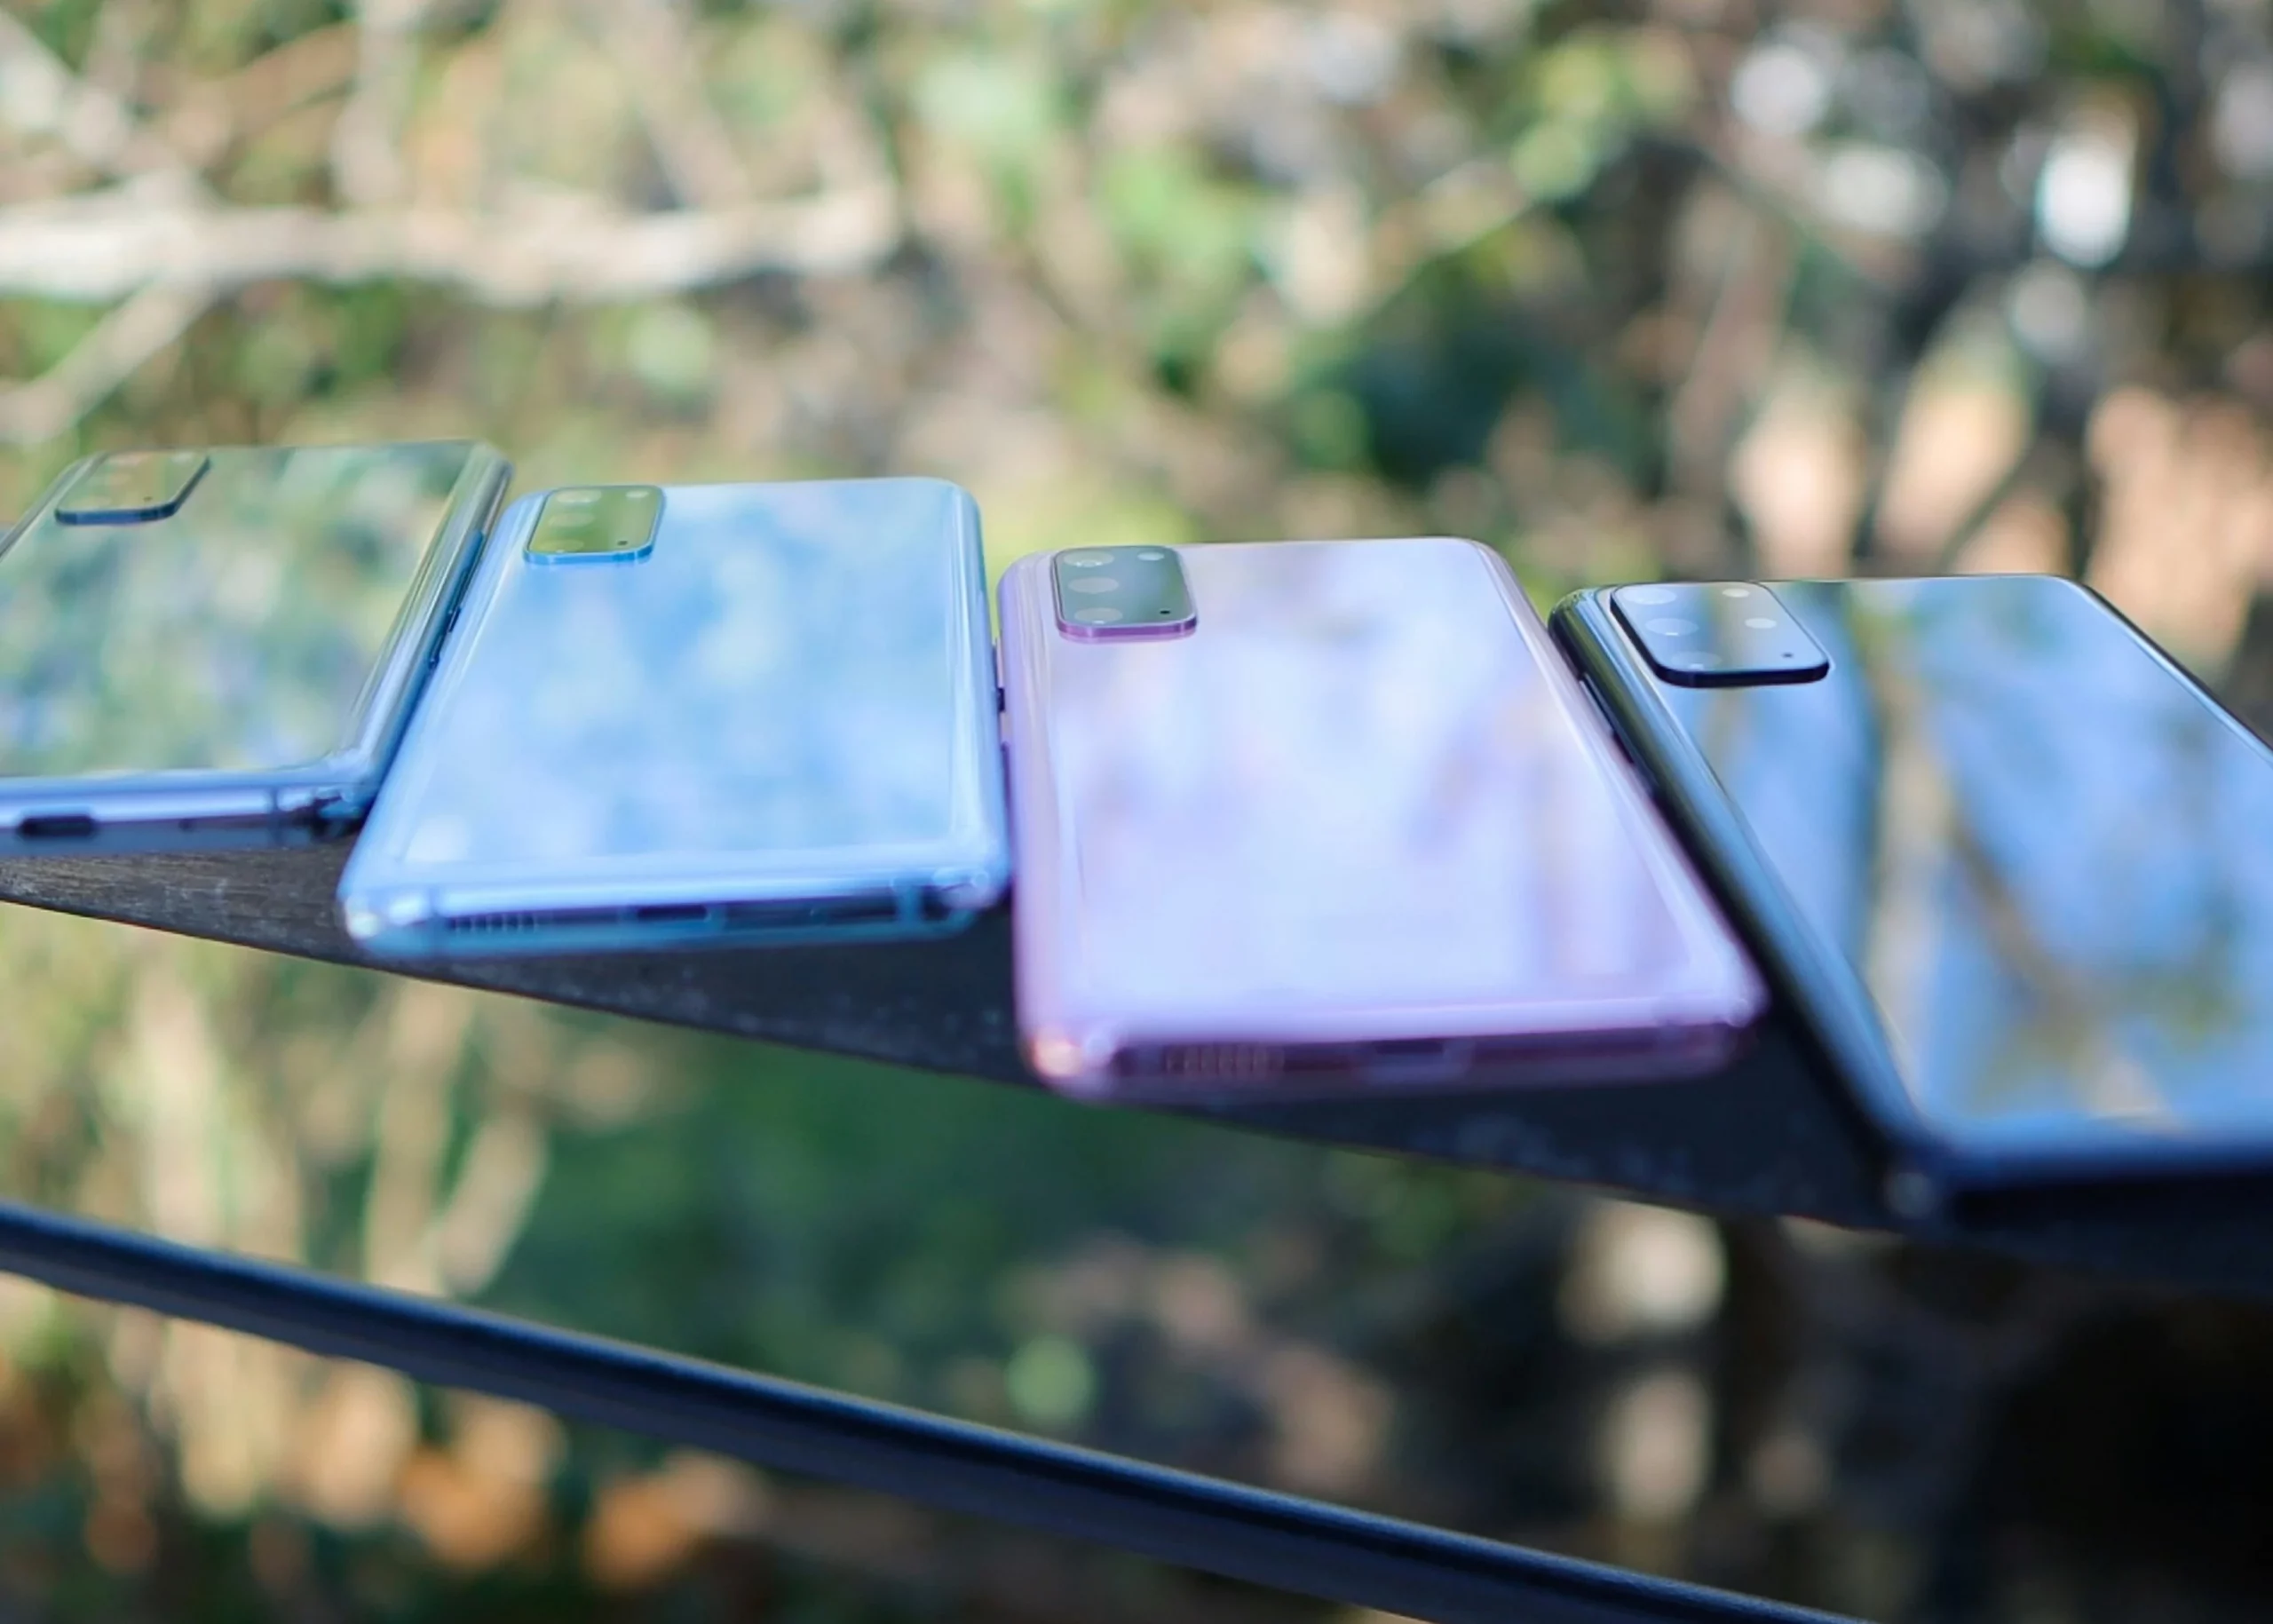
Image supplied.
“Rising component costs and differing vendor responses are reshaping the competitive landscape, but market share alone does not tell the full story,” said Hayden Hou, principal analyst at Omdia.
“As vendors make different trade-offs between shipment scale, revenue and profitability, their performance needs to be assessed beyond unit shipments. More importantly, the strategic decisions made during this downturn could have lasting implications beyond the current cost cycle. Investments in new channel partnerships, device financing capabilities and stronger premium portfolios will help determine which vendors emerge with a more competitive and sustainable business model once cost pressures ease.”
Lucas Zhong, senior analyst at Omdia, said: “For vendors competing primarily on affordability, protecting profitability without sacrificing shipment scale has become an increasingly difficult balancing act. This pressure is particularly acute in emerging markets, where consumers are more price-sensitive and vendors rely heavily on entry-level devices with already thin profit margins.
“However, scaling back shipments to protect margins carries long-term risks, particularly for emerging vendors, as losing market presence can weaken brand visibility and channel mindshare, which may take years to rebuild. Rather than withdrawing across the board, vendors need to make more deliberate choices about where to compete, concentrating resources on markets and products that can sustain both profitability and market relevance.
“Looking ahead to the fourth quarter, new flagship launches, promotions and festive demand are unlikely to fully offset persistent supply-side pressures. Vendors will need to combine disciplined inventory management with more effective financing, trade-in and telco partnerships to sustain upgrades without relying on broad discounting.
“While shipment volumes remain under pressure, rising prices are gradually resetting consumer price expectations, potentially creating greater opportunities for higher-value devices in future replacement cycles. Vendors that can make these products more accessible and demonstrate meaningful improvements in the user experience will be better positioned for the next replacement cycle.”
| Worldwide smartphone market share split Omdia Preliminary Smartphone Market Pulse: 3Q26 | |||
| Vendor | 3Q26market share | 3Q25market share | |
| Samsung | 23% | 19% | |
| Apple | 22% | 18% | |
| Xiaomi | 12% | 14% | |
| OPPO | 9% | 12% | |
| vivo | 8% | 9% | |
| Others | 27% | 29% | |
 | |||
| Note: Preliminary estimates are subject to change on final release. Xiaomi includes Redmi and POCO, vivo includes iQOO. OPPO includes realme and OnePlus. Source: Omdia Smartphone Horizon Service (sell-in shipments), October2026 | |||
* Guido Russo is writer and contributor for Gadget.